Finding a chiropractor with insurance is only the first step toward controlling your costs. A clinic may accept your insurance card without being in-network for your exact plan, and a covered appointment can still involve a deductible, coinsurance or separately billed services. Before booking, confirm both the provider’s network status and the likely charges for your first visit. A little documentation now can make an unexpected bill much easier to prevent or challenge later.
Why “accepts insurance” is not a price guarantee
Three different questions often get bundled into one: Will the office submit a claim? Is the provider in your plan’s network? Does your plan cover the proposed treatment?
Accepting insurance does not necessarily mean being in-network. An out-of-network office may submit claims on your behalf, but your plan might pay less or provide no out-of-network benefits. Where permitted, the provider may also bill you for the difference between its charge and the insurer’s payment.
Even in-network care is not automatically inexpensive. You may owe the negotiated rate until you meet your deductible, or your benefits may impose a copay, coinsurance or visit limit. Treatment can also require prior authorization or documentation of medical necessity.
Keep these questions separate when comparing offices. For a broader explanation of plan types and benefit structures, review how chiropractic insurance plans work in NYC. The practical goal here is to turn those benefits into a written estimate for the care you actually expect to receive.
Verify a chiropractor with insurance for your exact plan
Start with your insurer’s provider directory, then call the member-services number on your insurance card. A directory listing is useful, but it should not be your only confirmation.
Give the insurer the chiropractor’s full name, office address and National Provider Identifier, or NPI, if available. Ask the clinic for the billing entity’s name and tax identification number when needed. The individual practitioner and the organization submitting the claim can both affect network verification.
Ask these specific questions:
- Is this practitioner in-network for my exact plan at this location?
- Is chiropractic treatment covered, and are referrals or prior authorizations required?
- How much of my applicable deductible remains, and what copay or coinsurance applies?
- Are there visit limits, and do chiropractic visits share a limit with other therapies?
- Are the proposed examination and treatment services covered when billed by this provider?
Record the representative’s name, call date and reference number. Save the directory listing or any written confirmation in your member portal.
Then ask the clinic to verify the same details. Benefits verification is an estimate, not a guarantee of payment. Claims can still depend on eligibility on the treatment date, coding, authorization and medical necessity. If the insurer and clinic give conflicting answers, resolve the discrepancy before scheduling nonurgent care.
Request a service-by-service estimate
When comparing a chiropractor with insurance, ask about the entire appointment rather than the price of an adjustment alone. A first visit may include an evaluation and treatment, and additional services may have separate billing rules.
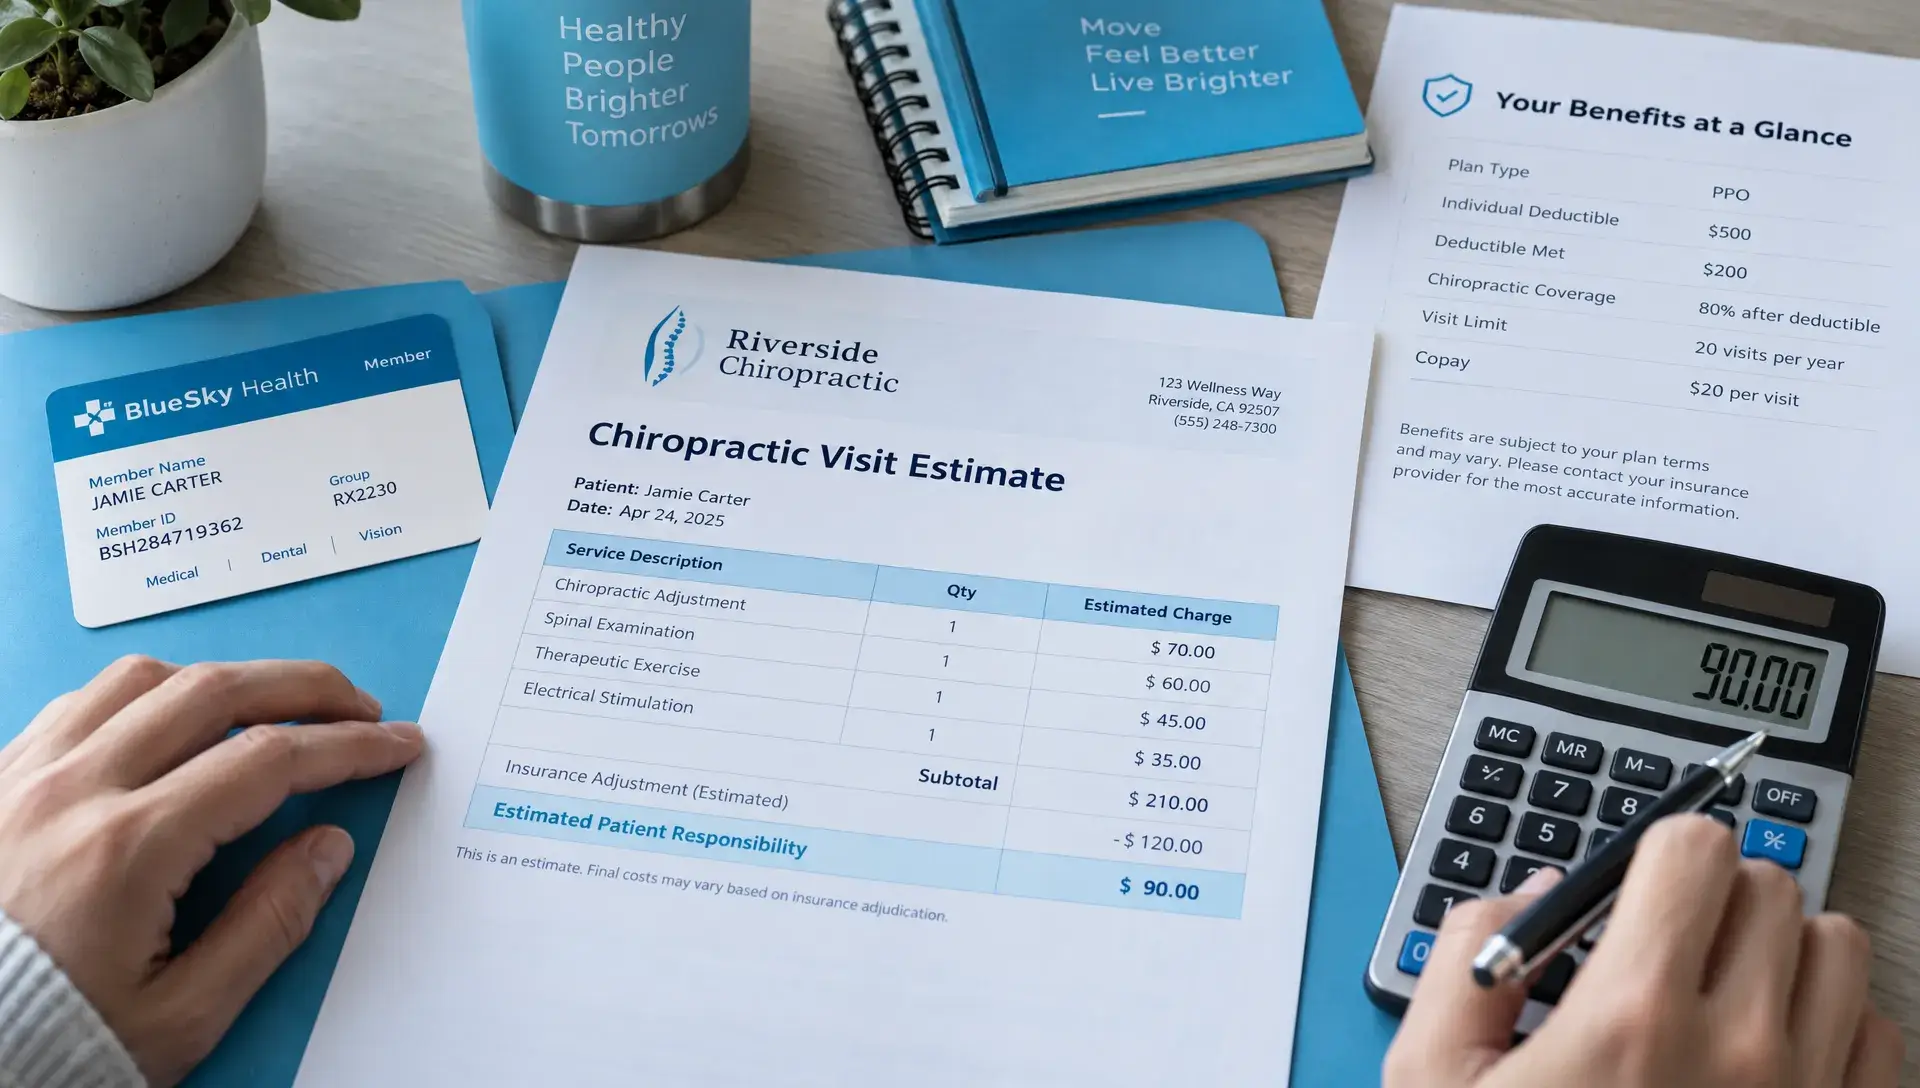
Request an itemized estimate that identifies the proposed services, anticipated billing codes and estimated patient responsibility. If the treatment plan cannot be determined until the examination, ask for the examination estimate first and a separate treatment estimate afterward.
| Potential charge | What to confirm before agreeing |
|---|---|
| Initial evaluation | Whether it is billed separately and what cost-sharing applies |
| Spinal manipulation | Whether your benefits cover the proposed service and require authorization |
| Therapeutic exercises or rehabilitation | Who performs and bills the service, and whether separate benefits or limits apply |
| Acupuncture | Whether your plan covers it for your condition and whether that practitioner is in-network |
| Imaging | Why it is needed, where it will be performed and whether that location is in-network |
| Supplies or optional services | Whether they are covered or require a separate cash payment |
For a clinic offering several types of care, do not assume that one provider’s network status covers every clinician or service. Ask which treatments are included in the estimate and which require a new cost discussion.
You can also request a clear boundary: “Please tell me the estimated cost before adding any service that is not included in this estimate.”
Calculate your likely costs, not just the copay
A chiropractor with insurance may still cost more than expected if you focus only on the copay shown on your card. Your plan may instead apply a deductible and coinsurance to particular services.
The allowed amount is the amount your insurer recognizes for a covered service. For covered in-network care, the provider generally must follow its contracted payment rules rather than charge you its full billed price on top of your required cost-sharing.
Consider this hypothetical example, not a quote from any clinic. Assume all services are covered and in-network, you have $75 left on your deductible and your plan requires 20% coinsurance after that deductible is met.
| Planned care | Hypothetical allowed amount | Estimated patient share |
|---|---|---|
| First evaluation and treatment | $150 | $90 |
| Four follow-up visits at $80 each | $320 | $64 |
| Total | $470 | $154 |
For the first visit, you pay the remaining $75 deductible plus 20% of the remaining $75, or another $15. Each subsequent $80 visit costs $16 under these assumptions.
Your actual calculation may differ because of copays, excluded services, claim-processing order or separate deductibles. Ask for an estimate covering the initial visit and a short course of follow-up care, not an open-ended treatment package.
Flag work injuries and accidents before billing
Before a chiropractor with insurance bills your regular health plan, tell the office if your symptoms followed a workplace injury or motor vehicle accident. Those circumstances may involve workers’ compensation or no-fault coverage rather than ordinary health benefits.
Describe what happened, when it happened and whether a claim has already been opened. For example, a manufacturing employee handling custom shafts and rollers should explain the lifting, repetition or awkward positioning involved rather than provide only a job title. Accurate injury details help the office determine which billing questions need clarification.
Ask whether the clinic handles the relevant claim type and what documents or authorizations it needs. Do not assume an office participates in those systems simply because it accepts commercial health insurance.
If coverage responsibility is disputed, contact the relevant insurer or claims administrator before committing to a series of nonurgent appointments.
Keep a written record before the first visit
Save your benefit confirmations, estimates and authorization details in one place. A short email to the office can summarize what you understand: the provider is in-network, the examination has an estimated patient cost and additional services will be discussed before they are performed.
The strongest billing safeguard when choosing a chiropractor with insurance is a record that connects the proposed care to your specific benefits. Ask the clinic to notify you before you approach a visit limit or when an authorization needs renewal. Also check whether unused visits reset by calendar year or another plan year.
Review payment forms before signing. Understand any card-on-file authorization, cancellation fee or agreement to pay for noncovered services. Request a copy for your records.
Cost clarity should accompany appropriate care. Alongside the financial checks, look for a thorough evaluation and measurable treatment goals rather than choosing solely on the lowest advertised price.
If the bill is higher than expected, compare the documents
Do not assume an unexpected balance is correct, but do not ignore it either. Start by comparing the clinic’s itemized bill with your insurer’s Explanation of Benefits, or EOB. An EOB explains claim processing; it is not itself a bill.
Check the treatment date, practitioner, services and patient-responsibility amount. If the clinic’s bill exceeds the EOB amount for covered in-network care, ask the billing team to explain the difference. The account may need updating, although separately excluded services require their own review.
Look at the insurer’s reason for any denial. A missing authorization, incorrect provider identifier or coding issue may require action from the clinic. A benefit exclusion or medical-necessity denial may require a formal appeal with supporting documentation.
When resolving a bill from a chiropractor with insurance, ask who will submit a corrected claim or appeal and when you should follow up. Request that the disputed amount be placed on hold while it is reviewed, and obtain confirmation if the office agrees.
Keep copies of every message and follow the appeal deadline stated in your plan documents or denial notice. If the charge is valid but unaffordable, ask about payment arrangements without assuming the clinic offers discounts or financing.
Understand the limits of surprise-billing protections
An unexpected bill is not automatically a legally protected “surprise bill.” The federal No Surprises Act covers specified situations, including many emergency services and certain out-of-network services received at in-network facilities. It generally does not protect you simply because you chose an out-of-network chiropractor’s ordinary office.
The CMS guide to medical billing rights explains these protections and the separate rules for uninsured or self-pay patients. If you are uninsured or choose not to use insurance, you can generally request a good faith estimate for scheduled care. Under the federal patient-provider dispute process, a bill at least $400 above the applicable provider’s estimate may qualify for review. Other requirements and deadlines apply.
New York also has protections for certain surprise medical bills. Whether they apply depends on the circumstances and your coverage. State-regulated insurance and self-funded employer plans can follow different regulatory paths.
For someone booking a chiropractor with insurance, these laws are a backstop, not a substitute for checking network status and benefits. If you believe a protected bill was handled incorrectly, contact your insurer and the appropriate regulator identified in your plan documents. Ordinary deductibles and valid coinsurance do not disappear because the amount was unexpected.
Frequently asked questions
Does an office that accepts my insurance have to be in-network? No. “Accepts insurance” may only mean the office submits claims. Confirm participation for your exact plan, practitioner, billing entity and location with both the insurer and clinic.
Can an in-network visit still leave me with a large bill? Yes. An unmet deductible, separately billed services or excluded treatments can increase your responsibility. Request an itemized estimate rather than relying on a general statement that the visit is covered.
Does prior authorization guarantee payment? No. Authorization may satisfy one requirement, but payment can still depend on eligibility, benefit terms, coding and other claim requirements. Keep the authorization details and confirm which services and dates it covers.
Should I pay cash even if I have coverage? Compare the written cash price with your estimated insured cost. Ask your insurer whether self-pay expenses would count toward your deductible; do not assume they will. Also clarify whether the provider can offer a cash arrangement under its contract.
What should I bring to a chiropractor with insurance? Bring your current insurance card, identification, relevant referral or authorization information and the estimate or benefit notes you collected. Tell the office about any work injury or accident claim before services are billed.
Ask about coverage before booking at Move Well MD
Move Well MD offers chiropractic care, acupuncture, physical therapy and pain management in Manhattan. Before scheduling, contact Move Well MD to ask whether the specific practitioner and planned services participate in your exact insurance plan.
Request an estimate for the initial evaluation, clarify which additional treatments could be billed separately and confirm the answers with your insurer. That gives you a clearer basis for deciding whether the appointment fits both your care needs and your budget.
