Medically reviewed by Ben Gruen, DC, Chiropractor
Yes, visit limits can apply even when your chiropractor accepts your insurance. Finding a result for “chiropractor near me accepts insurance” is a starting point, not confirmation that every appointment will be covered. Your plan may restrict the number of visits, require approval after an initial treatment period or share a visit allowance across chiropractic care and other therapies.
Before booking a series of appointments, confirm three things: how your plan counts visits, how many remain and what you would owe for the next appointment. Insurance acceptance alone does not answer any of those questions.
How chiropractic visit limits actually work
There is no single visit limit that applies to every insurance plan. Your benefit documents control, and two people with the same insurer can have different coverage through different employers or products.
A plan can also apply several restrictions at once. Having visits available does not automatically mean a particular treatment is covered.
| Coverage rule | What it means | What to verify |
|---|---|---|
| Annual visit cap | A maximum number of covered visits during a defined benefit period | The limit, reset date and any exceptions |
| Shared therapy allowance | Chiropractic care and specified therapies draw from one combined allowance | Which services share the limit |
| Authorization requirement | Approval is required before treatment or after an initial allowance | Approved visits, services and dates |
| Medical-necessity review | Continued coverage depends on clinical documentation | What records or reassessments are required |
| Dollar limit | Coverage is restricted by a monetary allowance rather than just a visit count | Which services count toward that allowance |
A hard cap generally means the benefit ends once the stated allowance is exhausted, unless the plan provides an exception or another applicable protection changes the outcome. A review threshold is different: additional visits may be considered after the provider submits supporting records.
Ask whether the benefit period follows the calendar year or another plan year. Do not assume that your allowance resets on January 1.
What “chiropractor near me accepts insurance” leaves unanswered
An office may accept an insurance card or submit claims without being in-network for your exact plan. Even an in-network provider cannot promise that all services performed during an appointment will be covered.
Move Well MD’s guide to checking coverage for the exact provider, location and services explains that distinction. For visit limits, take the verification one step further.
Ask your insurer these questions before scheduling repeated treatment:
- What is my chiropractic visit allowance? Confirm whether it is a firm maximum or a threshold for additional review.
- Which services share that allowance? Ask specifically about physical therapy, occupational therapy and other rehabilitation benefits.
- How many visits remain? Request both processed usage and any available information about pending claims.
- Are referrals or prior authorizations required? Confirm the responsible clinician, submission process and approval dates.
- What will I owe? Check your remaining deductible, copay or coinsurance and the treatment of noncovered services.
Verify network participation with both the insurer and the clinic using the clinician’s name, practice location and your exact plan name. Record the date and call reference number, then request written benefit information when available.
Choosing a nearby chiropractor who accepts your insurance should include checking the individual services planned for your appointment. An adjustment, evaluation, acupuncture session and rehabilitation service may fall under different coverage rules.
How to calculate your remaining covered visits
Start with the plan’s stated allowance, then subtract the visits that count against it. Include treatment at other practices and services that share the same benefit pool.
For example, suppose a hypothetical plan allows 20 combined chiropractic and physical therapy visits per benefit year. You have used eight chiropractic visits and four physical therapy visits, with two more qualifying visits awaiting claim processing.
Your insurer’s processed records might show eight visits remaining. Once the two pending visits are counted, the projected balance would be six. This example assumes every appointment counts as one visit under that particular plan.
The phrase “chiropractor near me accepts insurance” cannot tell you whether a portal’s remaining-visit total includes recent appointments. That is why the office’s treatment history and the insurer’s claim history should be compared.
Confirm what counts as a visit
Ask whether the initial evaluation, a reassessment or multiple services on the same day affect the allowance. Some benefits are tracked by visits, while certain approvals are expressed in units or specific procedure codes.
Also confirm whether using a different chiropractor changes anything. A plan-wide annual allowance generally follows the member, not the practice, so changing offices usually does not restart it.
Keep the benefit limit separate from an authorization balance. Approval for six visits does not necessarily mean you have six visits left under an annual cap.
What your next appointment could cost
Covered care is not necessarily free care. You may owe a deductible, copay or coinsurance even when you have visits remaining and the provider is in-network.
Consider a hypothetical appointment involving one covered service with an $80 in-network allowed amount. If $30 remains on your deductible and your plan then requires 25% coinsurance, your share would be:
$30 deductible + 25% of the remaining $50 = $42.50.
That calculation assumes the plan applies those rules in that order and there are no other charges. It is an illustration, not a Move Well MD price or an estimate for your plan.
A nearby chiropractor accepting your insurance may provide several services during one appointment. Ask for an estimate that identifies each proposed service, rather than relying on a single quoted “visit copay.”
Ask for a service-specific estimate
A posted price for a defined service, such as a fixed-price iPhone repair, tells you the charge. An insured healthcare estimate must also distinguish the billed charge, negotiated allowed amount and patient share.
Ask what happens if your visit allowance runs out before the claim is processed. Whether you can be billed may depend on the reason for nonpayment, your plan, the provider’s contract and applicable rules. Request advance notice of services the office expects insurance will not cover, along with the proposed self-pay amount.
Why medical necessity and prior authorization still matter
A visit allowance is a ceiling on potential coverage, not a promise that every visit below that ceiling will be paid. Your insurer may require documentation that treatment is appropriate for your condition and meets the plan’s medical-necessity criteria.
That documentation may include functional limitations, examination findings, treatment goals and progress at reassessment. A useful goal describes daily function, such as tolerating a work shift or walking farther, rather than simply scheduling an indefinite number of adjustments.
An insurance-accepting chiropractor near you may need authorization before continuing care. Ask whether approval covers the specific clinician, procedures, number of visits and treatment dates. HealthCare.gov explains that preauthorization is not a promise that the plan will cover the cost.
Maintenance or wellness care may be treated differently from active treatment for a documented condition. Ask how your plan defines that distinction rather than assuming that recurring appointments remain covered.
Medicare has its own service rules
Original Medicare’s chiropractic benefit covers qualifying manual manipulation of the spine to correct a vertebral subluxation, not every service offered in a chiropractic office. Medicare Advantage members should also check their plan’s network and authorization requirements.
The practical lesson is the same across coverage types: verify the treatment itself, not just the provider’s participation.
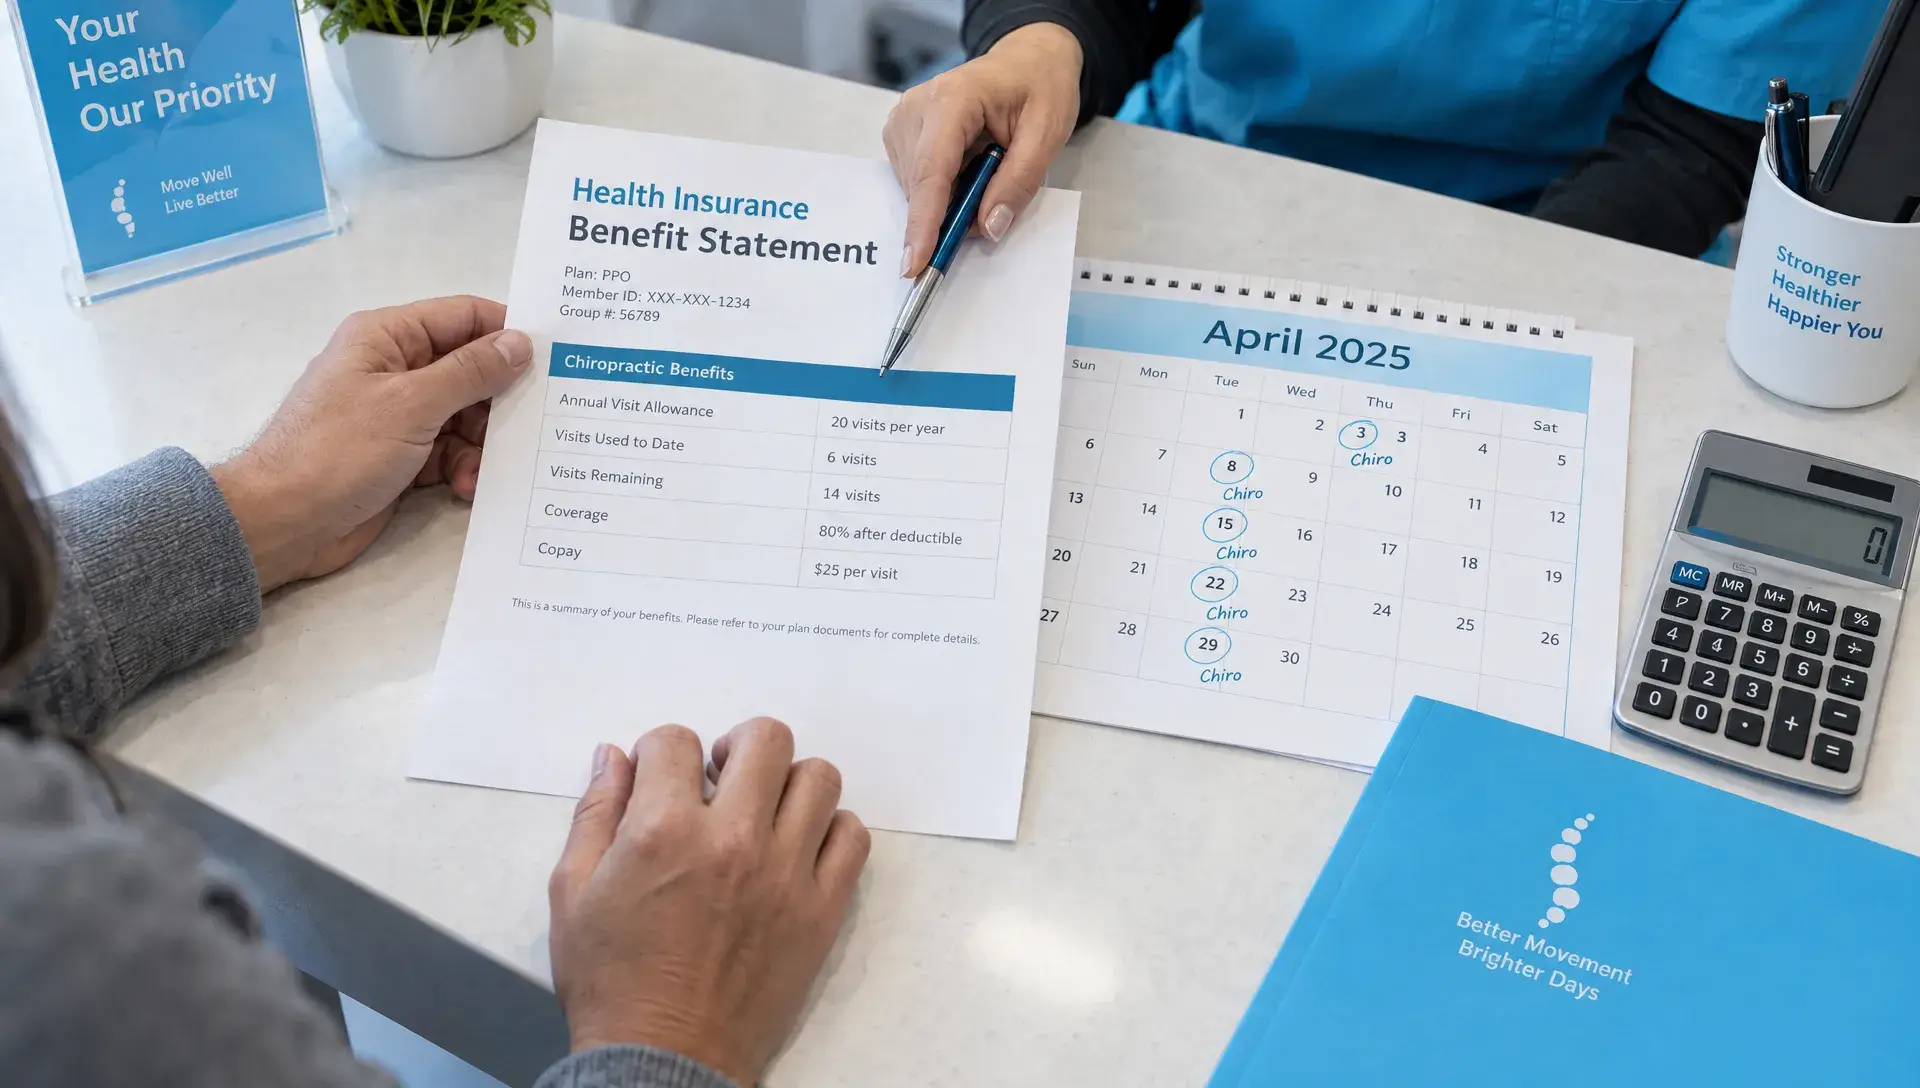
What to do when you are approaching the limit
Contact the insurer and clinic before the final covered appointment, not after receiving a bill. Ask whether the plan permits an extension and what documentation is required. A request for additional visits may be appropriate under some plans, but it cannot automatically override a firm benefit exclusion or exhausted allowance.
Review progress with your treating clinician. Discuss whether the current approach is helping, whether visit frequency should change and what appropriate home exercises or other care could support your goals. Treatment decisions should follow your clinical needs, not simply use up benefits before they expire.
Finding a chiropractor nearby who accepts your insurance also does not mean you must continue treatment there indefinitely. If progress is limited, ask whether reassessment or evaluation by another qualified healthcare professional is appropriate.
If a claim is denied
Read the explanation of benefits and identify the stated reason. An exhausted annual allowance, missing authorization, coding error and medical-necessity denial require different responses.
Ask the office to review possible billing errors. For a coverage dispute, follow your plan’s appeal instructions and deadlines, and request the clinical records relevant to the decision. Do not assume an appeal guarantees additional benefits.
If you choose to continue without coverage, request a written estimate before treatment. This guide to chiropractic care without insurance and ways to manage costs can help you compare the total cost of a proposed course of care, rather than only the price of one appointment.
Keep medical needs separate from insurance limits
An insurer declining further visits does not prove that you no longer need care. Likewise, having unused benefits does not establish that more treatment is necessary. Both situations call for a clinical discussion.
If your search for “chiropractor near me accepts insurance” began because of new or worsening symptoms, mention those symptoms before scheduling routine treatment. New loss of bladder or bowel control, numbness around the groin or rapidly worsening leg weakness warrants emergency evaluation. Significant trauma or fever with severe back pain also calls for prompt medical assessment.
Do not delay an appropriate medical evaluation while waiting for benefit verification or an authorization decision.
Frequently asked questions
Does accepting insurance mean my chiropractor is in-network? No. A practice may submit out-of-network claims or participate in only some of an insurer’s plans. Confirm the exact clinician, location and plan with both the office and insurer.
Will my visits reset if I switch chiropractors? Usually not when the limit applies to your plan’s annual benefit. Visits used at another practice may still count. Ask whether the allowance is shared across providers or services.
Can I get more visits if treatment is helping? Possibly, if your plan allows additional visits after review. Your clinician may need to submit progress records and a treatment rationale. Improvement alone does not guarantee an exception to a firm cap.
Does a new diagnosis create a new visit allowance? Not necessarily. Some limits apply across diagnoses, while others use different rules. A new complaint should be assessed accurately, not assigned a diagnosis or billing code to bypass a limit.
Should I book several appointments before benefits are confirmed? Ask about coverage, cancellation terms and possible self-pay responsibility first. A chiropractor near you who accepts insurance may still need to verify your remaining benefits before estimating a series of visits.
Confirm the next visit before committing to a series
Move Well MD offers acupuncture at three Manhattan offices: Lower Manhattan, Midtown and Columbus Circle. Its Lower Manhattan office also offers chiropractic care and therapeutic exercise. A licensed medical provider offers joint and trigger point injections. Ask the office about current participation for your specific plan and proposed provider, then confirm those details with your insurer.
When you contact Move Well MD about an appointment, have your insurance information and recent treatment history available. Request a service-specific estimate, clarify any authorization requirements and ask when coverage should be checked again. That gives you a more useful answer than “we accept insurance”: what your next appointment is likely to cost and which limits could affect continued care.
